Showing posts with label PRS. Show all posts

Wednesday, 25 May 2016

The Collective Licensing Question: To B2B or to B2C?

Music industry income can be divided into two main categories. There is business-to-consumer (B2C) income, the music that the public pays for directly. This includes record sales and live music. There is also business-to-business (B2B) income, music that is purchased by licensees from licensors. This includes broadcast music and the use of recorded music in public premises.
            As always, when it comes to matters of music and copyright, there are oddities and there are complexities. Curiously, the music that the public pays for is often private, whereas the music that is licensed between businesses is usually public. The B2C purchase of recorded music is regularly an individualistic affair. The consumer will select titles from the wide repertoire of music. They will choose when and where to listen to them. Each of these processes can take place in a solitary fashion. B2B licensing, in contrast, is the music of everyday life. This is particularly the case with the blanket licensing of music for radio stations, bars and shops. In these situations it is the collection societies who perform the task of the ‘2’. They sit between the licensor and licensee. If a music user obtains a blanket licence it will give them unfettered access to the entire repertoire of music of the collection society’s members. As I have written elsewhere, this process provides a reversal of Lord Macaulay’s oft-quoted beliefs. He argued that copyright ‘produces all the effects which the general voice of mankind attributes to monopoly ... to make articles scarce, to make them dear, and to make them bad’. The music industries’ most obvious monopolies are the collection societies. Collective licensing makes music abundant and it prices it democratically.
            The second issue is that the categories of B2C and B2B are not clear-cut. Although records and gigs usually classify as B2C, they include an element that can be considered B2B: the songwriting copyright. This money is passed from record companies and venue owners to composers and publishers by means of the collection societies. However, although the specifics of this income move from business to business, it is the consumer who generates the money. This income is built into the dealer price of recordings and forms part of the ticket price of gigs. This is Will Page’s viewpoint in his influential Adding Up the Music Industry reports. It is in fact possible to extend this line of thinking to the entirety of collection society income. In the final analysis, the consumer pays the copyright royalties for broadcast music: with public service broadcasting they are built into the licence fee; with commercial broadcasting they form part of the cost of the goods that are being advertised. And it is the consumer who foots the bill for the use of the collection societies’ music in public premises: this expense is added to the costs of the products that the premises are trying to sell.
This is not the perspective of the collection societies, however. They maintain that all of their transactions – broadcast, online, public performance or recorded media – should be categorised as business-to-business. Responding to a Monopolies and Mergers Commission (MMC) enquiry, PRS stated that ‘our primary customers are our members and affiliates but in our capacity as a rights licensing body, the licensee can be seen as a customer’. The MMC reported that ‘PRS did not accept that the ultimate music user, the listener, was its customer’. This outlook is reflected in the PRS for Music website, which is divided between sections for its licensor members and its licensee customers. There is no portal for listeners. PPL’s website is similarly divided between a section for its members and a section for music users. MCPS shares this twin perspective. When I worked for the company in the late 1990s, the executive director, Chris Martin, encouraged us to think of the society as being an estate agent, facilitating the sale and purchase of (intellectual) property. The concern was not with the music listeners, the people who actually had to live in these musical buildings.
The collection society’s B2B perspective has been influential. MMC investigations into PPL in 1988 and PRS in 1997 aimed to find out whether these societies were operating in the ‘public interest’. Their reports dealt with a circumscribed ‘public’, however. They dealt solely with the interests of licensors and licensees. In each case the MMC sought the correct balance between the amounts music users should pay and the amounts music creators should receive. Ultimately, they endorsed the practice of the collection societies ‘because the convenience they offer to both the owner and the user of copyright is unlikely to be matched by any other means’. They did not consider the listener.
The raison d’être of the collection societies is ‘to do collectively what creators cannot effectively do for themselves’. This is putting them in jeopardy, however, as what seemed ‘unlikely’ in the 1980s and 1990s is less so today. Creators are breaking ranks. Record company members of PPL are self-administering the income from streaming. Many publisher members of MCPS are also withdrawing from this field, as they too feel that they can negotiate higher streaming income licences on their own. These manoeuvres weaken the collection societies. They are losing out on a significant area of income, which has a knock-on effect for their cost-effectiveness as a whole. The collection societies also face the prospect of blockchain technology, which could make it possible for any of their members - whether large conglomerates or individual writers or musicians – to self-administer their rights. Graham Davies of PRS is fatalistic about this. He has stated, ‘If there were a new model which meant that our members didn’t need PRS that would be fine in principle. We should disappear because we would no longer add any value’.
This is B2B thinking. It is restricted to the value that collection societies hold for licensors and licensees. There is, however, a consumer value in collective licensing. If the collection societies go they will take blanket licensing with them. This will be disastrous. We are already witnessing its effects in streaming: the repertoire of even the biggest providers is patchy, principally because the biggest stars are holding out for more pay. Its effects will be felt more profoundly when it comes to the licensing of broadcasters and public premises. If we lose blanket licensing in these areas then music really will become more expensive and scarce. It is time, therefore, to start collectively thinking B2C.  

Monday, 9 November 2015

It's Not a Game of Monopoly

In an earlier blog entry, I found myself arguing with Lord Macaulay’s famous 1841 speech about the extension of copyright and its impact on the free trade of ideas. Macaulay argued that: ‘Copyright is monopoly, and produces all the effects which the general voice of mankind attributes to monopoly. .... The effect of monopoly generally is to make articles scarce, to make them dear, and to make them bad’.
In contrast, I suggested that music collection societies, which operate as natural monopolies in most countries, produce the opposite effects. Through their blanket licences they help to make music accessible and they sometimes make it cheap. In fact, in their ability to facilitate the business-to-business trade in music, they provide the context in which the public is able to receive a great deal of its music for free. They also help us to access a variety of music, as most of their licensing schemes provide standard rates. Thus it costs users no more to play a Beyoncé record than it does for them to play one Bis.
In addition, I argued that it is those artists who manage to gain individual control over their copyrights who are most likely to commit the evil that Maccaulay describes. It has generally been established and successful performers, such as Taylor Swift, Prince or Thom Yorke, who have managed to escape blanket licensing, whether that is the licensing of a record company or the licensing of a collection society. There are, of course, many positives about the degree of control that they have been able to gain over their careers. This control has nevertheless enabled them to make their work scarce (it doesn’t appear on streaming services) and to sometimes made it dear (as those forced to purchase 1989 on CD will testify).
Collection societies have, in general, been transparent and fairly even-handed. Their licensing schemes are made public and they offer standard terms. There are some injustices, nonetheless. PRS, for example, has had policies that divert income from popular music towards classical repertoire. MCPS, meanwhile, operates licensing schemes that become cheaper the higher up you go. Smaller record companies have to pay licences on the basis of the number of records of manufactured, while larger companies pay on the basis of the number of copies sold. The former have to pay their bills upfront; the latter are invoiced at a later date. Larger companies also pay lower commission rates and benefit from further economies of scale if they use MCPS to licence throughout Europe.
These various concessions don’t compare, however, to the secrecy and inconsistency that surrounds streaming deals. While some artists are escaping monopolies in order not to appear on streaming platforms, record companies and publishers are escaping monopolies in order to deal directly with the same sites. As I have previously documented, record companies maintain that streaming falls under the ‘making available’ right and they believe it is analogous to the sale of sound recordings rather than the broadcast of digital radio. As a consequence they have been able to escape the monopolistic licensing that public performance would entail. They have conducted their own deals with streaming companies and they have avoided the 50% royalty that PPL accords to performing artists.
In some ways, this isn’t a great break with tradition. Record companies have always made most of their deals directly. The same is not true of the publishing companies: the majority of their mechanical and performance licensing has taken place via the monopolistic rates and regulations of the collection societies. By making direct deals with the streaming companies they are entering unchartered waters. And this is precisely what attracts them: they want to escape those collective rules. It’s a complicated business nonetheless. Although record companies have convinced themselves that streaming is largely ‘mechanical’ in nature, the publishing world regards it as being equally divided between the performing and mechanical rights. However, while it is relatively easy for publishing companies to withdraw from MCPS and to self-administer the mechanical right for streaming purposes, they have no such jurisdiction over the performing right. Songwriters assign this right to their collection societies, rather than to their publishers. Consequently, in this area it is the collection societies who have control.
In Europe, the publishers’ solution to this problem has been to form ‘Special Purpose Vehicles’ with the collection societies. These SPVs entitle the publishers to deal directly with streaming companies and secure terms that cover both the performing and mechanical rights. Any terms reached must be agreed by the collection societies, however. Once the royalties have been calculated the income will make its way to artists either via their collection societies (the performing right share, presumably) or directly from their publishers (if this aspect of the mechanical right is escaping the collection societies it will mark another another area of income that is less readily identifiable as recorded music).
The publishers argue that licensing directly enables them to negotiate higher royalties for their artists, as they escape the flat demands of the collection societies. They also argue that this method is more efficient for the streaming companies, as these deals can be completed more quickly and can expand beyond the home country remit of the collection societies. Songwriters are less comfortable. According to the Music Managers Forum many of them would prefer for streaming income to fall under the remit of the collection societies:
possibly because they trust their CMO [collection society] more than their label or publisher; or because payments via CMOs often circumvent contractual terms that enable labels or publishers to retain income; or because they feel collective licensing is fairer to all, because everyone earns the same per play fees, rather than bigger artists or rights owners having a better deal.
Nevertheless, if they are signed with a major publisher, they will find that they have no choice. Sony/ATV has entered into an SPV with PRS and GEMA, Universal has one with SACEM, Warner/Chappel has SPVs with a number of collection societies including PRS, while BMG has a joint venture with GEMA. Meanwhile, Kobalt, who are probably the most innovative publishing company operating today, have actually bought the collection society, AMRA, which they employ to conduct their SPVs.
            And what does this mean for the consumer? In the first instance, it might make some music scarce. Although these direct deals are of potential benefit to the streaming companies because they can licence one publisher for multiple territories, the drawback is that they have to do deals with each publisher individually. Some catalogues may well be left out. These joint ventures might also make music dear. If publishers are able to negotiate higher royalties for their songwriters, then the consumer may well end up paying for them. This could be directly, via subscription charges, or indirectly, via the advertising fees that result from fremium services. In addition, some music might end up being dearer than others, which in turn might make it scarce. The withdrawal from monopoly tumbles on and on . . .  

Wednesday, 21 October 2015

I’ve Been Making Available All My Life

In recent blog entries I have been taking a look at the recording and publishing industries, as well as at mechanical and performing rights. Mechanical rights, which are also known as reproduction rights, incorporate the right to copy a work and the right to issue copies of a work to the public. Performing rights encompass the right to perform to work in public and the right to communicate the work to the public, which includes broadcasting.
In ‘Adding Up the Publishing and Recording Industries 2014’ I stressed the monetary importance of performing right for both songwriters and recording artists. Under PRS for Music rules, songwriters are automatically entitled to 50% of income whenever their song is licensed for performance, whether this be in a live setting or via a broadcast. Similarly, under the ‘equitable remuneration’ rules operated by PPL, recording artists are entitled to 50% of income whenever their recordings are played in public premises or are broadcast on radio or TV. In both cases these royalties are safeguarded: they cannot be recouped from advances.
In ‘Broadcast Y’Self Fitter’ I stressed the difference between classifying digital income as a performance or a mechanical right. If it is regarded as the former, being considered more akin to broadcasting, then artists as well as songwriters can be entitled to as much as 50% of the royalties. If it is regarded as the latter, being instead associated with physical recordings, the recording artist’s royalty rate can drop to something like 15%.
            I’m not alone in having this interest. Since uploading my last blog entry, the Music Managers Forum has published Dissecting the Digital Dollar: How Streaming Services are Licensed and the Challenges Artists Now Face. It is an important document, providing a detailed and lucid account of copyright and royalties in the digital age. It also provides further detail for the case that I have been making.
            One of the best ways to highlight injustices and inconsistencies in respect of royalties is to compare the activities of the collection societies, publishers and record labels. Publishers’ collection societies view the broadcasting of songs as involving both a mechanical and a performance right. In Britain, both the Performing Right Society (PRS) and the Mechanical-Copyright Protection Society (MCPS) have collected income for radio broadcasts. The performing and mechanical rights are present for online licensing as well, whether this is for online radio, downloads or streams. Consequently, the umbrella society, PRS for Music, operates joint licences to capture both of these forms of copyright.
There are differences in the way that income is divided, however. Perhaps understandably, as the format has an affinity with the sales of records in record shops, downloads are regarded as being more mechanical: 75% of royalties collected under the relevant joint licensing scheme go to MCPS and 25% to PRS. Online radio witnesses the reverse: 75% of income goes to PRS and 25% to MCPS. Again, this is understandable, as radio leans more towards the communication right that is enshrined in PRS activity, than it does towards the right to copy, which is patrolled by MCPS. Streaming sits in between: here the money from joint licensing is divided 50/50 between MCPS and PRS. These splits have implications for songwriters. They might receive similar overall shares in each area: for example, both the mechanical and performance income could be divided 75/25 between artists and publishers. As stated above, however, it is only the performance income that is safeguarded against advances: 50% goes directly to the songwriter and cannot be recouped.
If the recording world were to have parity with music publishing, streaming would be regarded as having an equal split between mechanical and performing rights. It would then follow that record companies would collect the 50% of the streaming royalty that relates to the mechanical right themselves. From this income, they would pay their recording artists a similar royalty to their income for physical sales: this would result in a new recording artist receiving an approximate 15% share. The recording artist should do better when it comes to the performing right. 50% of streaming income would be collected by the relevant performing right society, which in the UK is Phonographic Performance Ltd (PPL). This income would itself then be split 50/50, with half going to the record company and half to the recording artist.
But this doesn’t happen. Record companies collect the whole of the streaming income. According to PPL’s own literature, the labels regard both downloading and streaming as involving the mechanical right only. Their 2011 Annual Report states:
PPL’s online revenues remain limited as the majority of online sound recording licensing is carried out directly by rights owners. This reflects the prevailing view of record companies that downloading and on-demand streaming is analogous to the distribution of sound recordings, a traditional record company function.
Running somewhat counter to this argument, the record companies’ also claim that recording artists are not entitled to ‘equitable remuneration’ when it comes to downloading and streaming because this is an area in which performing rights operate differently.
            Here they refer to the ‘making available’ right, which was formulated during World Intellectual Property Organisation treaties of 1996 and enshrined in EU law in 2001. Dissecting the Digital Dollar outlines the origins of this right:
the communication control, where defined in copyright law, traditionally related to conventional broadcasting which, while easily extended to webcasting, might not apply to other kinds of digital transmission. To ensure digital communication of this kind would still be restricted by copyright, and perhaps to distinguish it from the existing controls that covered broadcasting, some rights owners lobbied to have a separate control added to copyright law called ‘making available’.
The activity controlled by this law is ‘electronic transmission in such a way that members of the public may access the recording from a place and at a time individually chosen by them’. As such, it clearly encompasses downloading, but does not encompass online radio (as a result online income in this area is collected by PPL). The record companies believe that the ‘making available’ right encompasses streaming as well. However, as the MMF report states, ‘not all artists agree’ with this point of view. As illustrated by the way that the publishing sector deals with streaming income, this activity can be regarded as akin to both broadcasting and to record sales.
            Why does any of this matter? ‘Making available’ is the only area of sound recording performance rights that is exempt from ‘equitable remuneration’. Consequently, artists are not guaranteed 50% of this income. Instead, it can be collected by record companies directly and some artists will therefore be on a standard royalty rate as low as 15%. What is more, any royalties collected can be recouped from advances.
            Dissecting the Digital Dollar includes a survey conducted with artist managers. Their responses to two questions are particularly telling. 78% of respondents believed that equitable remuneration should exist for all digital services, including both downloads and streams. However, when asked if they know how collection societies proportion streaming income according to the mechanical right and the performing right, only 3% replied in the affirmative.  

Monday, 5 October 2015

Adding up the Publishing and Recording Industries 2014

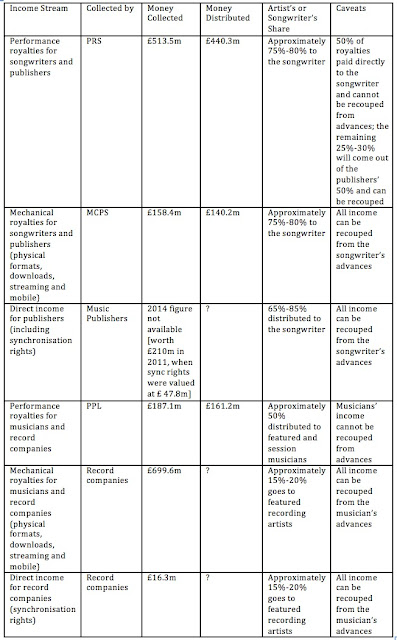
Following on from the previous two blog entries, which took a comparative look at UK collection societies and the income earned by live and recorded music, I’ve made a stab at presenting UK recording and publishing income for 2014.
           The statistics come from a variety of sources and it is risky to contrast them in this manner. In addition, I don’t have privileged access to information. What the figures should help indicate, however, is the relative health of each area. I’ve also made a stab at indicating what proportion of money will go to the songwriter or performing artist albeit that, unless the money is paid to them directly by a collection society, there are plenty of deductions and reductions that can be added to the percentages given in the final column. Significantly and spitefully, I have left out the money from live music, other than performance royalties that PRS collects for songwriters and publishers.


While the collection societies and the British record industries’ trade body BPI are reasonably good at indicating the money that has come into the UK, they are less forthcoming about the money that is leaving. The PRS, MCPS and PPL figures include income that is derived via reciprocal links with foreign collection societies, but they fail to state how much is going in the opposite direction. We don’t know how much money is going to foreign songwriters, publishers, record companies and musicians. Moreover, the record company figures also say nothing about the nationality of the musicians who will be receiving the royalties, nor do they mention the record companies’ countries of origin.
            According to Will Page, there was a time when publishers’ income was divided 40:40:20 between performing, mechanical and synchronisation streams. The figures above would indicate that the split is now divided something like 70:22:8. While this new division highlights the decline of record sales, it distorts the income that can be made from sync rights, which in overall terms has risen considerably in the past few years. In fact, the £47.8m figure given in relation to songwriting sync rights seems like a conservative reckoning, as does the £16.3m for sound recording sync rights. The latter figure comes from IFPI, but in 2011 BPI were regarding this income as nearer to £22m.
While the mechanical royalties for songwriters and publishers are certainly declining, these figures show them to be in better health than some PRS for Music information would have us believe. The PRS for Music Financial Review for 2014 lists recorded music as being worth £63.1m. The higher figure of £140.2m quoted here comes from MCPS’s own Report and Statements and includes the mechanical income that is derived from online licensing and broadcasting income.
            PRS and MCPS generally operate joint licences when it comes to online income (there are also a few minor income streams that are jointly licenced between PRS and PPL). There are no figures available to show how this income is split: PRS for Music instead publish a total figure of £79.7m. This figure is around 22% of the £363.8m that record companies derive from downloads (£249m) and streaming (£115m). The proportion of this money that makes its way to performing artists is much debated.
            But how much money in royalties is going to songwriters and artists overall?  A final, admittedly rough, outcome would reveal something like the following:
  • Performance royalties for songwriters: £374m (roughly two-thirds of which is non-recoupable)
  • Mechanical royalties for songwriters: £119m (recoupable)
  • Sync rights for songwriters: £33m (recoupable)
  • Performance royalties for musicians: £81m (non-recoupable)
  • Mechanical royalties for musicians: £122m (recoupable)
  • Sync rights for musicians: £3m (recoupable)
The money’s in the publishing; it is also in performance.

Friday, 18 September 2015

Broadcast Y'Self Fitter

While it might not be the most exciting game in town, it is instructive to compare the remits of the UK's music collection societies. A Venn diagram would place PRS in the middle. It overlaps with PPL in that it is concerned with the performing right: the income that is derived from the licensing of music to public premises and broadcasters. However, whereas PRS collects this money for songwriters and publishers, PPL collects this money for performers and record companies.
            MCPS overlaps with PRS because it has the same constituency: songwriters and publishers. The money that MCPS collects on their behalf comes from the mechanical licensing of music: the copyright income that arises when songs are reproduced in recorded form, whether this be the sale of physical formats, the broadcast of recorded music on radio and television, the online reproduction of recorded music, the synchronisation of recorded music with moving images or various lesser categories, such as the mechanical reproduction of music in greetings cards. There is no mechanical collection society for performers and record companies. The distribution of money from these sources is something that record companies handle themselves.
            It is appropriate that MCPS and PPL sit at the margins of a Venn diagram, as they collect less money than PRS.  I have written elsewhere about one of the crucial monetary differences between PRS and MCPS. Songwriters and publishers assign the performing right to PRS. The collection society therefore owns this right and collects income from all performance uses. MCPS, in contrast, merely administers the mechanical right. Its members can opt to self-licence the use of their music for films, adverts and some TV broadcasts. Many chose to do so, as the fees that they can extract will be larger than can be derived from MCPS’s blanket licences.
Another crucial difference between PRS and MCPS is the way that money is distributed to songwriters. The standard arrangement at PRS is that 50% of royalties go directly to the songwriter, while 50% of royalties go to the publisher. The songwriter might also receive a share of the publisher’s 50% of royalties: a common deals are for total income to be split 75/25 or 80/20 in the songwriter’s favour. There is nevertheless a difference between the 50% that is paid directly to the songwriter and the 25%-30% of their income that PRS distributes to the publisher. The 25%-30% can be used to pay off the publisher’s advances; the 50% cannot. When it comes to mechanical royalties, a songwriter will enjoy a similar 75/25 or 80/20 split. MCPS distributes its income directly to the publisher, however. Consequently, the entire share that is due to the songwriter can be used to pay off their advances. A songwriter will not receive any mechanical income until these advances have been recouped.
            PPL has similarities with both societies. In response to the European Union’s Rental Directive, it elected in 1996 to distribute 50% of its income directly to performers and 50% to record companies. Here the society parallels PRS in that the artist’s share is safeguarded: it cannot be used to recoup record company advances. This is enshrined in law. In 1996 an amendment was made to the Copyright, Designs and Patents Act concerning the ‘right to equitable remuneration for exploitation of sound recording’. The amendment states that where a recording is ‘played in public’ or is 'communicated to the public' then this performance right ‘may not be assigned by the performer except to a collecting society for the purpose of enabling it to enforce the right on his behalf’. Crucially, this means that artists are not permitted to sign over the performance right in their recordings to their record companies. There is, however, one exception to the 'communication' provisions. Keen readers of updates to the 1988 Act are referred back to the earlier clause 182CA(1), which covers 'electronic transmission in such a way that members of the public may access the recording from a place and at a time individually chosen by them'. This is the 'making available right', which was added to copyright law following the WIPO Treaties of 1996. The electronic transmission being referred to here relates specifically to the online delivery of music. In this sole area of 'communication', performers are not entitled to 'equitable remuneration'. 
            Reflecting this state of affairs, the majority of online income falls outside of PPL's remit. The society’s Annual Review for 2011 states that:
PPL’s online revenues remain limited as the majority of online sound recording licensing is carried out directly by rights owners. This reflects the prevailing view of record companies that downloading and on-demand streaming is analogous to the distribution of sound recordings, a traditional record company function.
Their 2012 Annual Review states:
The scope of PPL’s online licensing rights remains largely limited to online radio, and income from this sector showed further growth in 2O12, albeit from a modest base. The majority of online usage of sound recordings is directly licensed by rightholders and PPL maintains a regular dialogue with its members as to the appropriate extent of PPL’s online licensing.
And in 2013:
The number of small online radio broadcasters licensed by PPL continued to grow, facilitated by the introduction of ‘self-service’ online licensing functionality on the PPL website. Revenue growth from such licensees however, was offset by a decline in revenue from the larger online radio services licensed by PPL, where the market has moved to more interactive online services licensed directly by rightsholders.
The latest Review, for 2014, tells us:
Overall growth in Broadcast & Online licensing income of 1% was delivered in 2014. This was achieved despite increased competition from new online services, which are largely licensed directly by PPL’s members.
What do record companies have to gain by regarding downloading and streaming as analogous to the distribution of sound recordings, on the one hand, or being classified as part of the 'making available right', on the other? First, it means that this income goes directly to the record companies rather than to PPL. Consequently, the money that is due to artists is not safeguarded against their advances: it will instead be used to recoup them. Secondly, it means that the record companies do not have to abide by PPL’s 50/50 rules for splitting income equitably with performers. Many recording artists are, in fact, receiving a far lower percentage of online royalties than this. You’ve probably heard about the fuss they’re making.

Thursday, 10 September 2015

Sympathy for the Mechanical

Although I’m not always sure of the motivations, there is a politics to the reporting of music industry sectors. In particular, there has been a desire to emphasise the health of the live music industry at the expense of recorded music.
The statistics that have been most widely used in support of this scenario come from Adding Up the Music Industry, a series of reports issued by PRS for Music. Sadly these reports are no longer compiled: the last of them concerns revenues for 2011. It calculates the total money generated by the UK music industry in this year at £3,793m. Out of this figure £1,057 comes from business-to-business income and £2,736m from business-to-consumer. The latter is divided into £1,112m for recorded music and £1,624m for live music.
And so live music triumphs over all other comers. It is this outcome that many analysts have taken up and run with. The reports have their problems, however. Live income is compiled in a different manner to the other streams. As well as documenting the primary market – the money spent on purchasing tickets from ticket agents and venues – the figure includes secondary ticketing and ancillary spend. Secondary ticketing is money derived from the resale of tickets. Although the report states that this business model is ‘legitimate under UK law and is an established practice’ it is somewhat contentious. Moreover, none of the money from these sales goes to writers, musicians, publishers or record companies. At the very least this income is comparable to the second hand sale of records, an income stream that is omitted from the figure for recorded music. Under a different legal system it could be considered more akin to bootlegging. The report calculates its worth at £208m.
Ancillary spend is the extra money that is spent at gigs and festivals: the purchase of ‘merchandise, food, beverages, parking and public transport’. It is questionable whether the money spent on food, drink and transport should be included as part of music industry income. Some money from these sales might trickle through to a few performing artists, but it will be tangential and minimal, and in these instances should be included in the business-to-business figures, rather than business-to-consumer. Moreover, although these sales are included in the live income stream, money spent on food, drink and parking when going record shopping is not included in recorded music. This is the case even when the record shops are serving food and drink themselves.
Artists can make money from merchandise. There are famous cases where bands have made more money from t-shirt sales than they have from ticket sales. It is unfair, however, to include the sales of merchandise in the live tally while omitting it from recorded music: these reports do not include the sale of t-shirts and other merchandise in record shops.
It is difficult to calculate how much ancillary spend is worth as the 2011 report fails to provide precise figures. The best it offers is that festivals and arenas each account for ‘around 25 percent of the market’ and that ancillary spend at festivals is equal to ’95 percent of the average face value ticket per person’ while the ‘level for most other venue sizes was between 35 and 50 percent’. At the very least, then, ancillary spend is equivalent to a third of the money spent on primary tickets. The live income stream can therefore be broken down into £208m for secondary ticket sales, £472m for ancillary spend and £944m for primary ticket sales. It is only the latter figure that can effectively be compared with the statistics for recorded music. Looked at this way, live income is the lower of the two.
Recorded music is unfairly represented in other ways. In 2011 PRS for Music reported £65m income for ‘mechanical revenues’, i.e. the money that songwriters and publishers earn from record sales. Adding up the Music Industry contrasts the ‘continued decline of the recorded music market’ with the ‘phenomenal revenues’ earned in the live sector. However, live income for PRS for Music was £23m, which is lower than the mechanical income derived from its MCPS alliance.
In addition, the summarising table in the report equates ‘recorded music’ solely with business-to-consumer income. The total of £1,112m is made up of ‘payments for physical music products, downloads-to-own and subscriptions’. This obfuscates the fact that there is plenty of recorded music income that is derived business-to-business. A substantial amount of the £448m that is attributed here to PRS for Music comes from the use of recordings. Away from the main breakdown of figures, the report itself allocates £101.6m of PRS income to ‘recorded music’. Sound recordings also contribute to its other income streams: broadcast & online, public performance, and international. It should be conceded that live music also contributes to each of these remaining areas of business-to-business income, albeit that it is recorded music that dominates when it comes to the income generated by radio, television, the internet and the use of music in public premises.
Moreover, while PRS for Music owns the performance right in its members’ works, MCPS does not have complete jurisdiction over the mechanical right. Its members can opt to self-licence the use of recorded music for films, adverts and some television programmes. As such, recorded music makes up a significant proportion of the music publishers’ direct income. Out of the £210m that is allocated to them in this report, £48m comes from these sync rights. Ultimately, the mechanical income for songwriters and publishers is holding up better than much industry reporting would lead us to believe.
There is, in addition, plenty of business-to-business income that makes its way to record companies and recording artists. Recorded music is responsible for all of the £80m income that is attributed to PPL and the £220m accorded to ‘record label direct revenues’. The latter figure, in fact, includes some PPL revenue, as it is made up of ‘music synchronisation, “360 degree” artist deals, concerts, music-related TV production, broadcasting and public performance’.
Because of the way the figures are reported, it is impossible to make an accurate tally for the income derived from sound recordings. Recorded music is, however, worth considerably more than the £1,112m highlighted in Adding up the Music Industry. For the vast majority of professional songwriters and musicians it provides more money than live music does. While the same is obviously true for record companies, it applies to music publishers as well.
There are good reasons why some academics have seized upon PRS’s analysis: they like to emphasise the freedoms of the live music scene in comparison with the tyranny of being signed to a record company. PRS also has a performance emphasis. It is, after all, the ‘performing right’ that is enshrined in the society’s initials. Unlike the Musicians’ Union, however, it does not campaign to keep music live: it collects money from the performance of records as much as it does from performance in person. The reasons why PRS have chosen to under-represent recorded music in their reports are therefore obscure. Finally, I should concede that I have my own biases. Although I do think I’ve provided a fairer way of reading the statistics, I also know that I’m a record man. My main pleasures in popular music have always come from recordings. 

Thursday, 18 September 2014

Fight for Your Right to Equitable Remuneration!


The British Copyright Act of 1911 contains a crucial line. Clause 19(1) states that ‘Copyright shall subsist in records, perforated rolls, and other contrivances by means of which sounds may be mechanically reproduced, in like manner as if such contrivances were musical works’. In order to establish a songwriting copyright in relation to sound recordings (and other ‘mechanical’ contrivances) there was a need to equate records with sheet music, i.e. ‘musical works’. Artistic copyright was strongest in relation to the printed word or score. Here, authors and their publishers received copyright income in relation to each copy sold. Consequently, one of the methods used to establish this equivalence between sheet music and sound recordings was to claim that the groove of a record was a form of writing (see ‘Audio Books’ for further details).
As a result of clause 19(1), songwriters received a copyright share in record sales, just as they had done in sheet music. It was originally deemed that 5% of the retail price of record should go to the authors of musical works. In anticipation of this measure, various ‘mechanical’ copyright collection societies were formed. These eventually morphed into the Mechanical-Copyright Protection Society (MCPS), which was established in 1924.
There was another consequence of the Copyright Act. Despite its intentions, it demonstrated that there were differences between mechanical reproduction and musical works. When it came to musical works, the author of the work was deemed to be the songwriter. Songwriters were therefore the ‘first owners’ of these works and were free to exercise their rights as they wished. Clause 19(1) crated a separate copyright for mechanical reproducers, now commonly referred to as sound recording copyright. The owners of this copyright were not the songwriters, however, nor were they usually the performers who appeared on the records. Clause 19(1) instead decided that ‘the owner of such original plate [the master copy of the record] at the time when such plate was made shall be deemed to be the author of the work’. The owners of these plates were the record companies. Accordingly, they were regarded as the first owners of the sound recording copyright.
Today, most recording artists receive payment in the form of advances from their record companies. If they recoup those advances, they also receive royalties. As Peter Martland has outlined, there was a different method of paying popular musicians and singers during the first three decades of the twentieth century. While a few opera singers and classical musicians received royalties, this was rare for popular artists. The most successful of these might be paid a yearly retainer to record exclusively for a record company. When it came to making records they would also receive a session fee but no royalties. Lesser-known popular artists would receive session fees only. Essentially, they were being paid a one-off sum to perform in a recording studio.
At the time of the 1911 Copyright Act, these recorded performances were usually destined for domestic consumption: most records were played in people’s homes. In the coming years recorded performances increasingly came to be heard in performance contexts. As reproduction technology improved, records were more regularly played in public spaces. They also began to be broadcast, forming part of the repertoire of radio networks from the early 1920s onwards. And by the late 1920s recordings could be heard in films.
By this time the performance right for musical works was beginning to be established. The Performing Right Society (PRS) had been formed to administer this right in 1914 and had gradually gained converts amongst songwriters, composers and publishing companies. With the advent of new technologies, performance right income became increasingly important. However, despite the desire of clause 19(1) to establish copyright parity between mechanical reproduction and musical works, it was not generally assumed that this right existed in relation to sound recordings.
In 1933 the Gramophone Company brought a test case to clarify this point. Carwadine & Co had been playing recorded music in their coffee shops; the Gramophone Company deemed this to be a breach of their performing rights. In the resulting court case it was ruled in the record company’s favour that clause 19(1) did warrant a performing right in sound recordings. In the following year Britain’s two major record companies, the Gramophone Company (which by then had become EMI) and Decca Records, joined forces to create Phonographic Performance Ltd (PPL) to administer the performing right in sound recordings.
As the owners of sound recording copyrights, record companies were now legally entitled to all the performance right income earned by their records. The recording artists, who they had hired to perform on these records, were not due any money when these records were themselves ‘performed’. What followed is one of the quirks of copyright law. The first owners of the sound recording copyright shared their performance income with their recording artists even though, initially at least, there was no legal requirement for them to do so.
According to PPL’s own history, it was their choice to give the artists a share of this income. In their publicity materials they state, ‘This intelligent and far-sighted decision was particularly remarkable because of its voluntarily nature, bearing in mind that there was no legislative or other external pressure on PPL at the time’. In its early years PPL allocated 80% of its income to record companies and 20% to the artists on their records. These splits were amended in 1946; henceforth 67.5% went to the record companies, 20% to featured artists, and 12.5% to the Musicians’ Union (MU).
PPL also came under external pressure. Stephen Barnard believes that it was, in fact, the MU who were responsible for artists receiving a share of performance income. He has written that ‘Under the original [PPL] agreement, revenue received for public performance of records went direct to the participating companies, but this was modified in 1935 under pressure from the MU, whose members could in law claim no royalties for the public performance of their recorded work (the copyright resting with the companies themselves)’. He adds that it was ‘New negotiations between PPL and the MU’ that resulted in the share allocated to the MU in 1946. The MU’s position in these negotiations is understandable. For a long time the organisation campaigned against sound recordings, as it felt records provided a cheap and inferior alternative to its members live performance work. This stance was later embodied in the Union's slogan, ‘keep music live’. (Ironically, the 'keep music live' campaign, which was initiated in 1964, was funded by recordings: the MU didn't allocate the money it received from PPL to the artists who appeared on records, but instead used it collectively. The 'Phonographic Funds' were distributed in various ways: some money went to members who had fallen upon hard times, other funds were used to finance various large-scale orchestras, some was spent on a series of May Day dances, and a 'large proportion' was used for the Union's promotional campaign.) 
Why should PPL concede to the MU's demands? Sarah Thornton has listed several possible reasons. First among them is the fact that the Union helped PPL to maintain control of its repertoire, as they forbade their members from recording with non-PPL companies. Secondly, MU members monitored record performances and copyright infringement at a local level, something that the understaffed collection society was unable to do. In addition, John Williamson has suggested that 'fear on the part of the record companies of a recording strike and a challenge to PPL's collection arrangements meant that they were willing participants in post-war discussions with the MU'. It should nevertheless be noted that the MU was only receiving 12.5% of PPL's money - there was a further 20% that was allocated to artists, and this money was distributed directly to the owners of the sound recording copyrights. Moreover, PPL continued to pay artists a share of their income, despite the fact that records came to be seen as less of a direct rival to live performance. They also continued to do so despite the declining power and membership of the MU. It might be that another aspect of PPL's farsightedness was envisioning that the artists’ share would eventually be enshrined in law.
It took a long time to reach this point. Section 5 of the 1956 Copyright Act clarified that a performance right existed in sound recordings, but failed to mention any artist rights. The UK signed up to the 1961 Rome Convention, article 12 of which states that an 'equitable remuneration' is due when recordings are broadcast or communicated to the public. There is a lack of clarity in this article, however. It states that this remuneration should be paid to 'the performers, or to the producers of the phonograms, or to both', and that it can be divided by 'agreement between these parties' or by domestic law. It was not until the European Union ‘Rental Directive’ of 1992 that the matter was settled. Article 8(2) ruled that ‘Member States shall provide a right in order to ensure that a single equitable remuneration is paid by the user, if a phonogram published for commercial purposes, or a reproduction of such phonogram, is used for broadcasting by wireless means or for any communication to the public, and to ensure that this remuneration is shared between the relevant performers and phonogram producers’.
The UK’s Copyright, Designs and Patents Act was amended in respect of the Rental Directive. In 1996 a section titled ‘Right to equitable remuneration for exploitation of sound recording’ was added. Clause 182D(1) states that: ‘Where a commercially published sound recording of the whole or any substantial part of a qualifying performance - (a) is played in public, or (b) is communicated to the public […] the performer is entitled to equitable remuneration from the owner of the copyright in the sound recording’. PPL’s literature explains what they did next:
When considering this new legislation, and after lengthy deliberations, the PPL Board agreed that the performers should benefit by receiving 50% of all ‘qualifying’ income on a track by track basis. This was a voluntary decision as legislators declined to recommend any particular split of PPL income. This meant that every single performer, whether featured or non featured would have to register their details with PPL or one of the newly formed UK performer organisations to enable their royalties to be forwarded to them.
The featured performers are those who have an exclusive contract with the record company issuing the record. Non-featured performers are commonly session musicians and backing singers. PPL has fairly complicated methods for dividing this income between the two types of performer. In general, however, the income is split 65:35 between featured and non-featured artists. This revenue has become increasingly important. In 2012 IFPI noted that ‘Performance rights income now accounts for 6 per cent of record companies’ trade revenues worldwide’. It would be higher still if it weren’t for the fact that copyright legislation has forced record companies in some countries to share this income equitably with their artists.
Finally, I would like to return to clause 19(1) of the 1911 Copyright Act and its idea that the copyright in records should operate ‘in like manner’ to the copyright in musical works. The Rental Directive has brought a form of parity between writers and artists. When it comes to the performing right, the songwriter members of PRS commonly receive 50% of this income directly, while 50% is paid to their publishers. The songwriters’ share is safeguarded in this manner because members assign their performing right in their compositions to the collection society. Their income from this right does not have to be paid off against publisher advances. In a similar manner, recording artists now receive 50% of the performing right income directly and this too does not have to paid off against their record companies’ advances. There remains a fundamental difference, however. Artists may well receive a 50% share of the performing right in sound recordings, but this share has been established without any fundamental change being made to the authorship or ownership of sound recording copyrights. In the majority of cases these still belong to record companies. But, surely some light has been let in here? The performing right underlines a conceptual problem that exists when considering record companies to be the authors of sound recordings. If artists are now considered as equal partners in the performing right, why not make them equal partners in the underlying sound recording copyright as well?